Your Money Has More Than One Job
How to Prioritize Your Money When Everything Feels Important
You get a raise. Or maybe the car is finally paid off. Daycare ends. A debt disappears. For the first time in a while, there’s a little more room in the budget.
So, what happens to the money?
Save more for retirement? Put it toward college? Build your emergency savings? Pay down another debt? Take the family somewhere you’ve been talking about for years?
The problem isn’t that you don’t have anything worthwhile to do with it. The problem is that you have too many worthwhile things to do with it.
That’s where financial planning gets interesting.
Most of us aren’t deciding between something important and something completely unnecessary. We’re deciding between priorities that all have a legitimate claim on the same dollars. And the answer isn’t necessarily going to stay the same forever. So before asking where should this money go?, it can help to ask a different question:
What job does this money need to do next?
Because your money has more than one job.
Start With the Job, Not the Account
It’s easy to jump straight to the how.
Should I increase my retirement contribution? Open a 529 plan? Pay extra on the mortgage? Invest more?
Those can all be useful questions. But there’s another question worth asking first:
What am I trying to accomplish with this money?
Money you’ll need next year has a different job than money intended for a goal decades from now. Before choosing the tool, understand the job.
Four Ways to Think About the Jobs Your Money Has
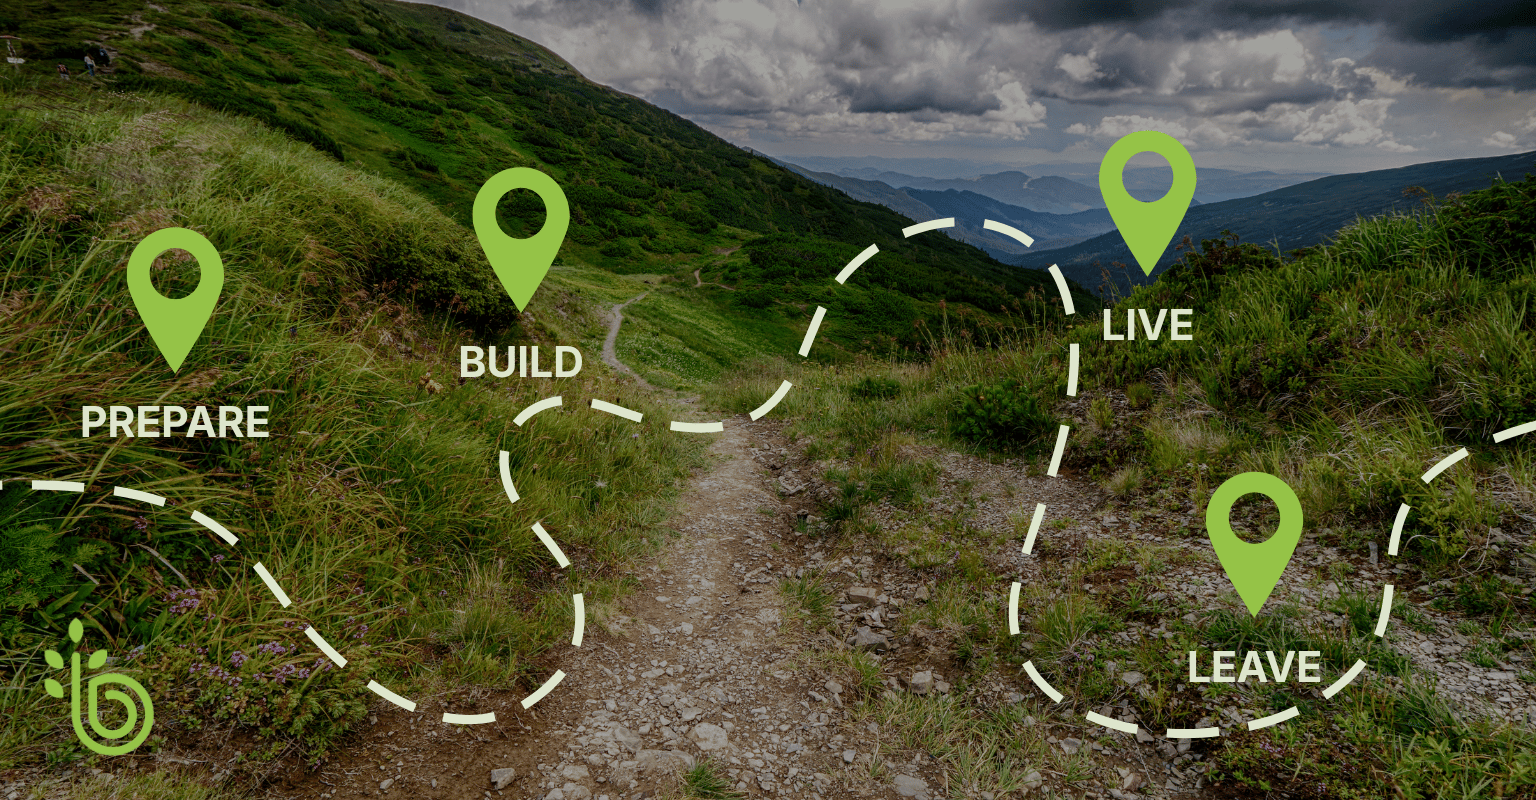
We use four broad conversation starters to help step back and see the bigger picture.
PREPARE — What do you need to be ready for?
Life doesn’t always follow the plan.
Emergency savings, unexpected expenses, healthcare costs and changes in income may all require financial preparation.
You can’t anticipate everything. The question is simply:
What do you want to be more prepared for?
BUILD — What future are you building?
Some of today’s money is intended for a future version of your life.
That might include retirement, education, investing or other long-term goals.
Those goals won’t necessarily happen at the same time, which makes the timeline part of the conversation.
LIVE — What matters today?
Financial planning isn’t only about someday.
Your money also supports your family, home, experiences, hobbies and everyday life.
Saving for the future matters. So does understanding what you want your money to make possible today.
LEAVE — Who or what matters beyond you?
You may want your resources to help children or grandchildren, support organizations you care about, or create a broader legacy. And Leave doesn’t necessarily mean waiting until you’re gone. Giving or helping family during your lifetime may be part of that picture, too.
These aren’t four separate buckets.
PREPARE • BUILD • LIVE • LEAVE aren’t a formula for dividing your money.
Some goals may even fit into more than one. College, for example, might represent Build, Live or Leave, depending on what providing an education means to your family.
The label isn’t the important part. Understanding why the goal matters to you is.
What Gets Your Next Dollar?
Imagine that starting tomorrow, you have an additional: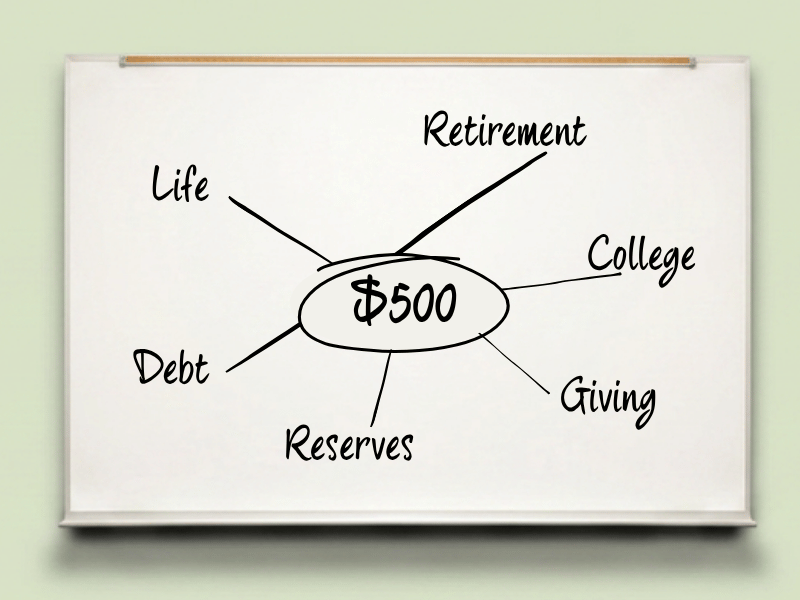
$500 per month.
Where does it go? Retirement? College? Emergency savings? Debt? Investing? Travel? Giving?
There isn’t enough information to determine one universally appropriate answer, and that’s the point.
Instead, ask:
Why did I choose that?
And then:
What worthwhile priority receives less because of that choice?
That’s opportunity cost: choosing one option means giving up the opportunity to use those same dollars somewhere else.
Financial planning often isn’t about choosing between good and bad. It’s choosing between good and good.
Now change the circumstances. What if you’ve fully funded your emergency savings? You receive a raise? Pay off a debt? Retirement gets closer? Your child approaches college?
Your answer might change.
Financial priorities change because life changes.
When Money Finishes One Job, Give It Another
Sometimes a financial obligation ends. You pay off the car. A student loan disappears. Your child finishes college. You receive a raise. Suddenly, cash flow is available that wasn’t available before.
That’s a useful time to ask:
What job should this money have now?
Depending on your circumstances, that could mean directing more toward retirement, education, reserves, debt, investing, giving, something you want to enjoy today, or another priority entirely.
The point isn’t where the money should go. It’s making the decision intentionally.
The Tool Should Follow the Goal
Once you understand what you’re trying to accomplish, you can evaluate the tools that might help.
Take college planning. Potential resources could include 529 plans, current cash flow, existing savings, scholarships and grants, student contributions, family assistance or borrowing.
But before asking:
Which account should I use?
ask:
What are we trying to provide?
When will we need the money?
What else are these dollars competing with?
Then you have context for evaluating the available options.
The tool should follow the goal, not define it.
Your Priorities Are Allowed to Change
What matters financially at 35 may not be what matters at 45 or 60. Children grow up. Careers change. Debts disappear. Parents age. Retirement gets closer. Goals that once felt distant become immediate. Your financial plan shouldn’t require your life to stand still.
Before making your next financial decision, ask:
What am I trying to accomplish?
When will I need this money?
What other priorities are competing for it?
What tradeoff am I making?
And ultimately:
What job does this money need to do next?
Start the Conversation at Home
College is one place where competing financial priorities can become especially clear.
The Family College Conversation is designed to help families think through what they want to provide, what else their money needs to accomplish, and which questions they still need to answer.
Explore the Family College Conversation
FAQs
How do I prioritize competing financial goals?
Start by identifying what each goal is intended to accomplish, when you’ll need the money, and what other priorities are competing for the same resources. Your circumstances, timeline, needs, and priorities can all influence how you choose to allocate your money.
Should I save for college or retirement first?
There isn’t one answer that applies to every family. Consider your overall financial situation, the timing of each goal, the resources already available, and the tradeoffs involved when deciding how to balance college and retirement priorities.
What should I do when I have extra money each month?
Before automatically directing additional cash flow toward one goal, consider what has changed and what your current priorities are. Depending on your circumstances, you may consider goals such as building cash reserves, reducing debt, retirement, education, investing, giving, or current lifestyle priorities.