College Financial Planning: Start With the Family Conversation
College Planning Starts Before You Choose How to Save
When families start thinking seriously about college, the conversation often moves quickly to numbers.
How much will college cost?
How much have we saved?
Should we be putting more into a 529 plan?
Those questions matter. But they may not be the best place to start.
Before deciding how you’re going to pay for college, there’s a more fundamental question worth discussing:
What role do we actually want to play in paying for our child’s education?
Because “we want to help pay for college” can mean very different things to different families.
What Does “Paying for College” Mean to Your Family?
Maybe you want to pay tuition. Maybe tuition and housing. Maybe you’d like to cover undergraduate expenses but expect your child to pay for graduate school. Maybe you’ve decided you’ll contribute a certain dollar amount and your child will be responsible for the rest.
Or perhaps the plan is simply to use what you’ve been able to save.
None of those answers tells us whether you’ve made a “good” or “bad” financial decision.
They tell us something much more useful:
What you’re actually planning for.
Before calculating how much you’ll need, define the commitment.
College Costs More Than Tuition
Once you’ve decided how much responsibility you’d like to take on, get specific about what that includes.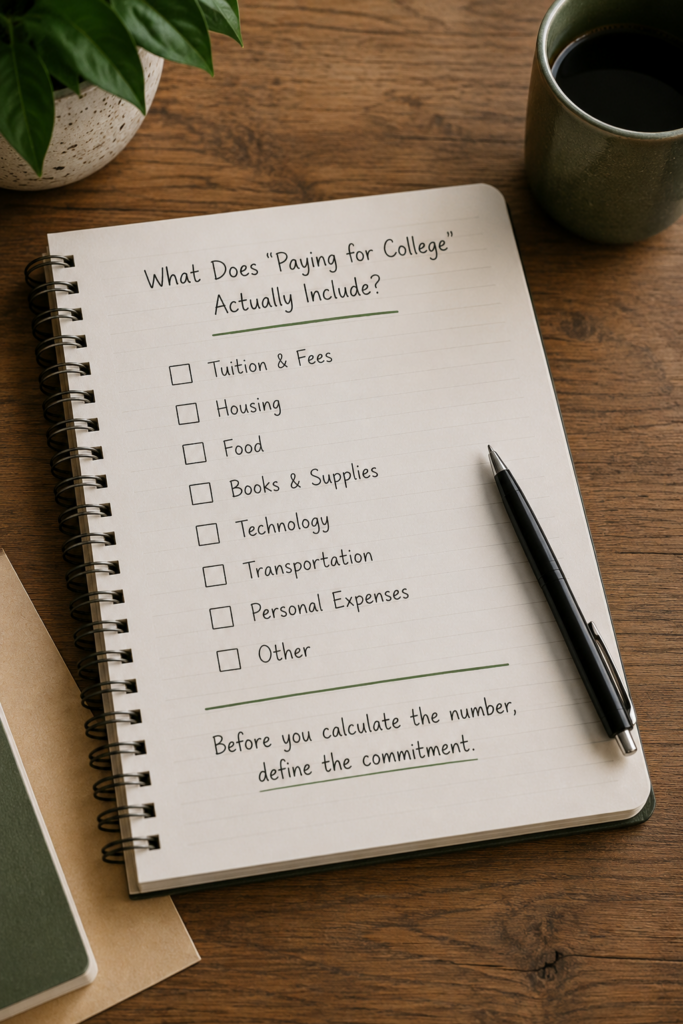
College expenses may involve more than tuition:
- Housing
- Food
- Books and supplies
- Technology
- Transportation
- Personal expenses
- Study abroad
- Other education-related costs
That makes a seemingly simple statement like “We’re paying for college” surprisingly complicated.
A better question might be:
Are we planning for college, or for a specific version of college?
Getting clear about that can make the financial conversation much more concrete.
What Role Will Your Student Play?
This can be one of the more important family conversations, and one that’s easy to postpone.
What, if anything, do you expect your child to contribute?
That might involve work, scholarships, savings, borrowing or another source of funding.
Again, there isn’t one answer that fits every family. What’s important is that parents and students understand the expectations.
A family can spend years preparing financially for college while never actually discussing what everyone believes the plan is.
Those assumptions can look very different once the first tuition bill arrives.
College Isn’t Your Only Financial Goal
Here’s where college planning gets harder.
You may genuinely want to help your child graduate with as little debt as possible. But at the same time, you may also be thinking about:
- Retirement
- Emergency savings
- Healthcare
- Debt
- Housing
- Other children
- Experiences you want to have as a family
- Other short- and long-term goals
Those aren’t distractions from college planning.
They’re part of the college-planning conversation.
The dollars available for one goal may also be needed for another.
So instead of asking only:
How much should we save for college?
Also ask:
How does college fit into our overall financial plan?
Every Yes Comes With a Tradeoff
Imagine you have another $500 each month. You could put it toward college.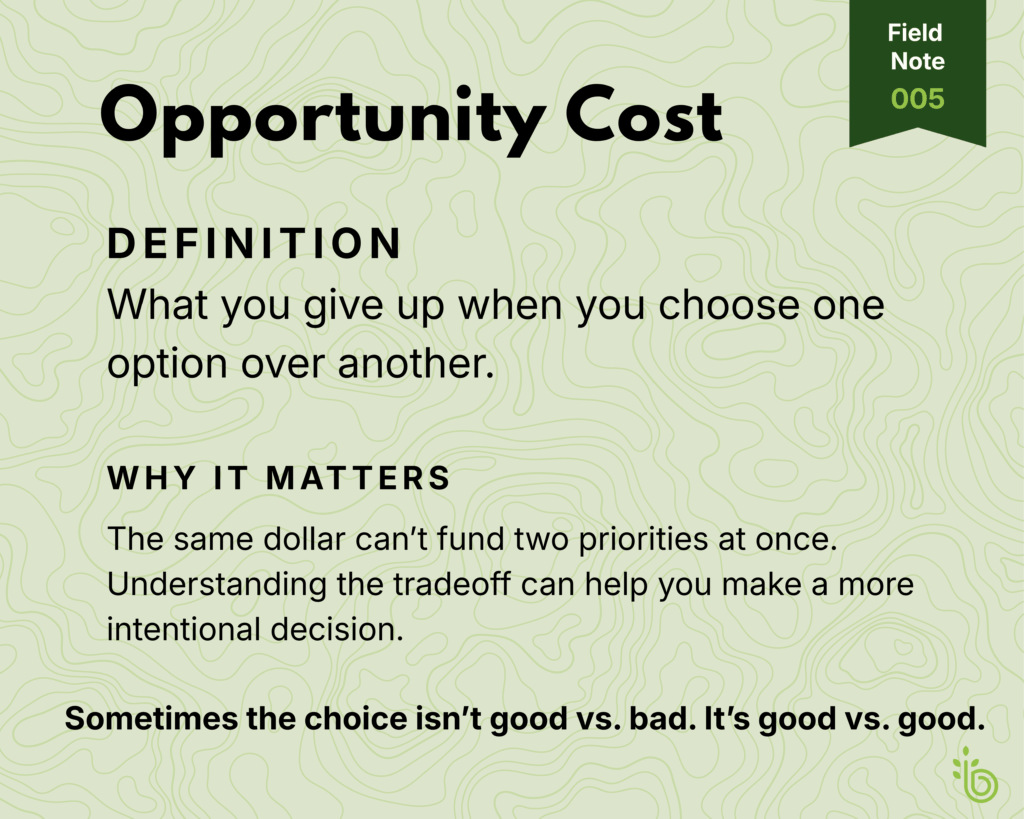
That’s a worthwhile goal. But maybe that same $500 could go toward retirement, cash reserves, debt or another family priority.
Choosing college doesn’t automatically make the decision right or wrong. Neither does choosing one of the alternatives. It simply means there’s a tradeoff.
That’s opportunity cost: choosing one use for your resources means giving up the opportunity to use those same resources somewhere else.
Understanding the tradeoff helps turn an automatic decision into an intentional one.
Your Answer May Change
College planning isn’t a decision you make once and never revisit.
Your circumstances may change.
Income can increase or decrease. A debt may be paid off. Emergency savings may become established. College may move from ten years away to two. Retirement may suddenly feel much closer.
When those things change, it’s reasonable to revisit the plan.
The question isn’t necessarily:
Did we choose correctly the first time?
It’s:
Given what we know today, what makes sense for our family now?
Decide the Goal. Then Consider the Tools.
Once you’ve defined what you’re trying to accomplish, you can begin considering how you might fund it.
Potential resources may include:
- 529 plans
- Current cash flow
- Existing savings
- Scholarships and grants
- Student contributions
- Family assistance
- Borrowing
Different resources come with different considerations, and the appropriate mix will depend on the family’s circumstances.
That’s why the sequence matters.
Goal first. Tools second.
Five Questions Worth Discussing Before You Pay for College
You don’t need a spreadsheet to start.
Sit down as a family and talk through these five questions:
- What do we actually want to provide?
- Which expenses do we consider part of our college commitment?
- What do we expect our child to contribute?
- What other financial priorities are competing for these dollars?
- What tradeoffs are we willing, or unwilling, to make?
You may not agree on every answer immediately.
That’s okay.
The purpose of the conversation isn’t to produce a perfect college plan in one sitting.
It’s to make sure everyone understands what you’re actually trying to accomplish before you start deciding how to accomplish it.
Start the Family College Conversation
College is a major financial goal for many families, but it’s still only one part of a much bigger financial life.
Our Family College Conversation workbook is designed to help you work through these questions together, from defining what you want to provide to considering how college fits alongside your other priorities.
Download & Explore the Family College Conversation
FAQs
How much should parents pay for college?
There isn’t one amount or percentage that’s appropriate for every family. Consider what you want to provide, the resources available, your child’s expected contribution, and how college funding fits alongside your other financial priorities.
What expenses should families consider when planning for college?
Depending on the school and student’s circumstances, college expenses can extend beyond tuition and may include housing, food, books and supplies, technology, transportation, personal expenses and other education-related costs.
Should parents prioritize college savings or retirement?
There isn’t one answer that applies to every family. The timing of each goal, available resources, existing savings, other financial needs and the tradeoffs involved can all affect how a family chooses to balance college and retirement.
When should families start talking about paying for college?
Families can benefit from discussing expectations before college decisions become immediate. The conversation can include what parents hope to provide, what the student may contribute, which expenses are included and how college fits with other family priorities.